
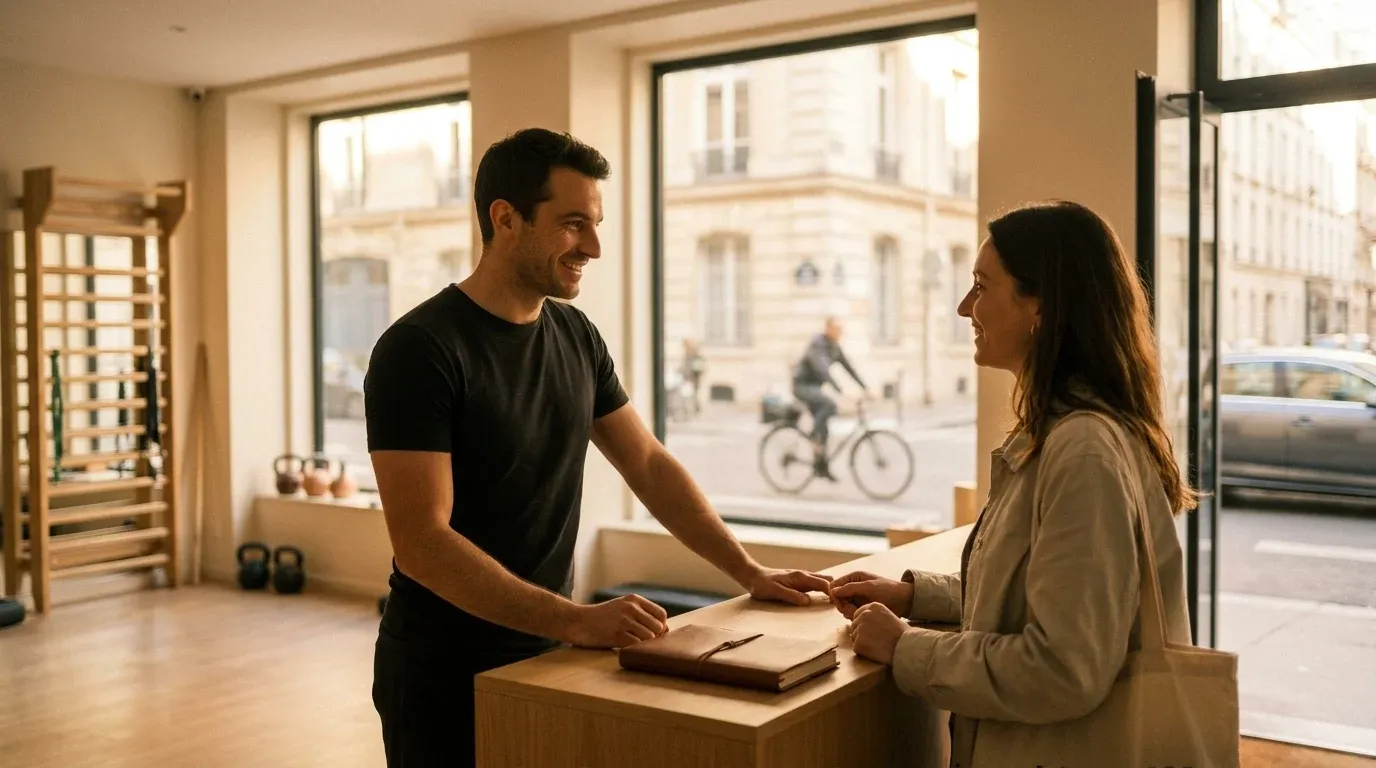
If you've walked past a budget gym chain lately, you've seen the playbook: massive signage, low monthly fees plastered on the windows, and a membership model built on volume over relationship. It works, at scale. But a September 26, 2026 market analysis of dense urban fitness markets documents something the chains haven't solved: proximity and personalized coaching are proving to be more durable competitive weapons than price.
The finding matters well beyond any single city. Independent gym operators globally are carving out real margin in markets that HVLP (high-volume, low-price) chains were supposed to own. The mechanism is worth understanding, whether you operate a facility or choose one.
What the Data Actually Shows
The September 2026 analysis identifies two variables that consistently separate thriving independents from struggling ones: physical proximity to the member's home or workplace, and a fixed coach-to-member relationship rather than rotating floor staff. Neither is a new idea. What's new is the margin data behind them.
Cross-market context arrives from the 2026 HFA Global Report, published September 14, 2026, covering fitness market conditions across 33 countries. The report shows that independent operators in mature urban fitness markets consistently index higher on member satisfaction scores and visit frequency compared to chain counterparts, despite spending significantly less on marketing per acquired member. That gap in visit frequency is critical: members who show up more often cancel less, and cancellation is where independent operators historically bleed.
For more on how the broader foot traffic landscape is shifting between HVLP facilities and boutique studios, HVLP vs Studios: Who's Actually Winning the Foot Traffic Surge? provides useful context from the same reporting period.
Rem Gym: A Case Study in Community Anchoring
The September 2026 analysis cites Rem Gym, one of the oldest continuously operating independent clubs in its urban market, as a benchmark case. Rem Gym hasn't competed on price for years. Its monthly membership sits well above the $30-to-$40 range that HVLP chains use as their entry hook. Yet retention rates hold significantly higher than the chain-gym urban average.
The explanation isn't a secret. Rem Gym's model is structured around fixed coach assignments: members are matched to a specific coach at enrollment, and that relationship is maintained as a default rather than an exception. The physical space is designed to signal neighborhood belonging. There's no corporate uniformity in the design language. Long-term members recognize staff by name. New members are introduced to existing ones deliberately, not accidentally.
That kind of intentional community construction doesn't happen by accident, and it doesn't scale easily. That's exactly the point.
The Operator Playbook Emerging From These Markets
Across the markets covered in both reports, a consistent set of practices separates independents that are growing from those that are losing ground to chains. Here's what the data supports:
- Micro-community programming. Small-group sessions organized around shared goals rather than class formats. Think eight-week strength blocks for members over 45, or recovery-focused programming for endurance athletes. These aren't general fitness classes. They're built for specific humans in a specific neighborhood.
- Fixed coach-to-member relationship models. Rather than assigning available floor staff to whoever walks in, leading independents formalize the coach relationship at the point of sale. Members know who their coach is before their first session. Research consistently supports that accountability relationships drive adherence. If you're evaluating how to structure your own training relationship, How Often Should You Train With a Personal Trainer? breaks down the frequency variables that affect outcomes.
- Physical design that signals place, not brand. Independent gyms that outperform chains in retention often look like they belong to their neighborhood. Local art, community bulletin boards, staff who live nearby. This is not aesthetic preference. It's strategic positioning that chains cannot authentically replicate at scale.
- Specialization by demographic need. Urban independents that anchor to specific populations, such as older adults focused on strength maintenance or women returning to training after a health event, build loyalty that broad-market chains struggle to match. The research on why strength training matters differently across life stages is well established. For operators targeting an older membership base, How to Choose a Trainer for Building Muscle After 40 reflects exactly the kind of content that resonates with the members independents are increasingly winning.
Why Human-Value Positioning Is a Structural Moat
Scale players have real advantages: national marketing budgets, app ecosystems, equipment refresh cycles funded by thousands of locations. What they don't have is the ability to manufacture authentic local relationships at a neighborhood level. Every time a chain tries to replicate community, it reads as performance. Members notice.
The HFA Global Report frames this as a structural moat for independents: human-value positioning. It's not a marketing message. It's an operational model. Coaches who know their members' injury history, sleep patterns, and life stressors are delivering something that a $35-per-month app-enabled gym membership cannot replicate.
This matters even more as the fitness industry moves toward data-driven personalization. Wearable platforms are raising the bar on what "personalized" means to a consumer. Oura's IPO Signals a Wearable Platform Shift documents how the expectation of real-time biometric responsiveness is reshaping what members expect from any fitness relationship. Independent gyms that integrate this data into coach-member conversations are ahead of the curve. Those that ignore it are ceding ground.
The Real Structural Risk: Data, Not Price
Here's where the analysis gets uncomfortable for independent operators. The competitive threat from HVLP chains is not price. Independents have already demonstrated they can survive and grow at a price premium. The structural risk is data infrastructure.
Large chains run sophisticated CRM systems and re-engagement automation that most independent operators don't have access to, or don't prioritize. When a member goes quiet for two weeks, a well-resourced chain knows within 48 hours and triggers an automated re-engagement sequence. A text, an offer, a coach check-in prompt. For many independent operators, that member quietly cancels without a single touchpoint after their last visit.
The 2026 HFA Global Report flags this explicitly: proximity advantage does not fully compensate for re-engagement infrastructure gaps. Independent operators that invest in even basic CRM tools, automated attendance tracking, and coach-prompted outreach see measurable retention improvements over those that rely on relationship warmth alone.
The math is straightforward. If your average member pays $120 per month and your churn rate drops by four percentage points annually because you catch lapsing members earlier, that's real revenue recovered without acquiring a single new member. For a 300-member gym, that retention improvement is worth tens of thousands of dollars per year.
What This Means If You're Choosing Where to Train
If you're not an operator but a member evaluating your options, the research here translates directly. The gyms that will deliver the best long-term results for most people are not necessarily the cheapest or the most conveniently branded. They're the ones where a specific coach knows your goals and your history, where the programming is built for people like you, and where showing up feels like returning to a place that knows you.
That's not sentiment. It's the structural predictor of adherence, and adherence is what actually produces outcomes. If you're navigating how to evaluate a coaching relationship before committing, How to Find a Personal Trainer You Can Actually Trust covers the specific signals worth looking for.
The fitness industry will continue consolidating at the mass-market end. HVLP chains will keep acquiring price-sensitive members and optimizing their unit economics. But the data from 33 markets in 2026 is clear: independent gyms that build on proximity, fixed coaching relationships, and genuine community programming are not being squeezed out. They're building something the chains can't buy.
The operators who close the data gap will make that moat nearly permanent.